TVS XL 100 Comfort EMI and Price for Easy Local Utility Travel
Overview
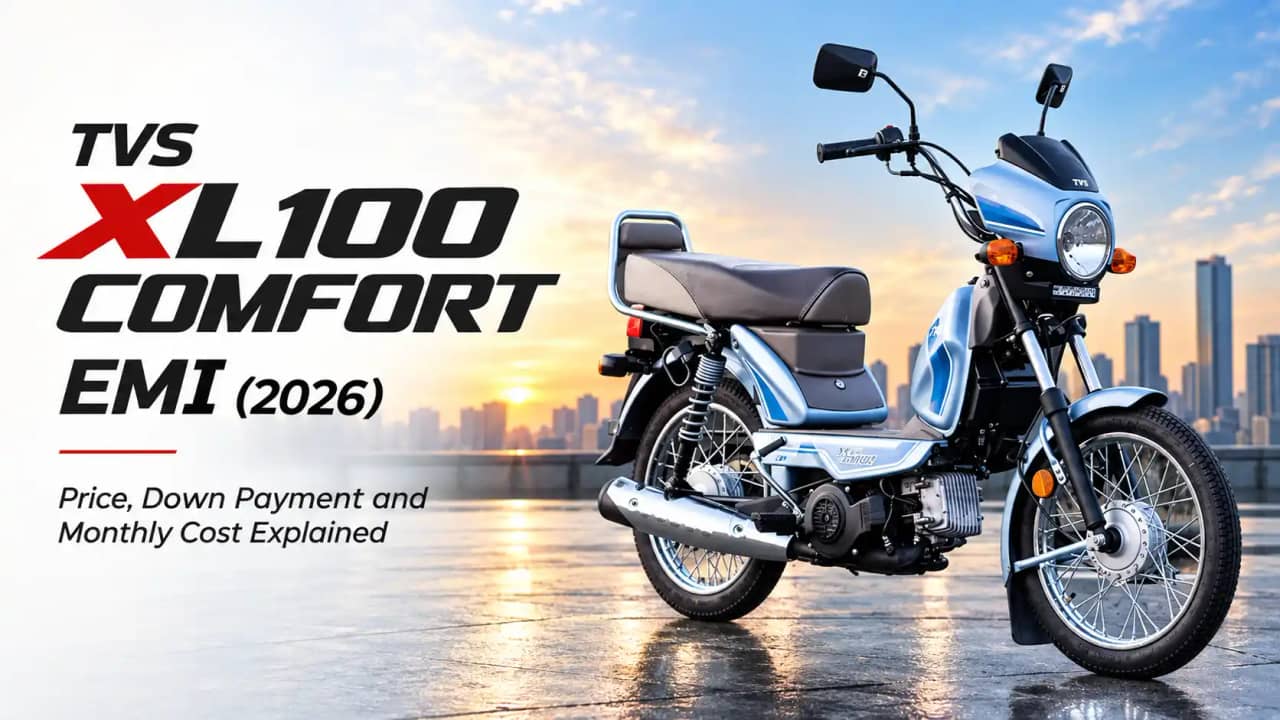
TVS XL 100 Comfort has a published starting reference of ₹60,480; the actual on-road price needs a local quote. This guide models ₹72,000, with a 20% down payment and a 36-month EMI of about ₹1,941 at 13% illustrative interest. It explains financing, city charges and ownership spending, with particular attention to starting convenience and small-loan charges. Confirm the variant and lender offer before booking.
The XL 100 Comfort i-Touchstart carries a manufacturer price reference of ₹60,480, making the starting system and intended local use important to its financing decision. This guide assumes ₹72,000 on road. Registration, insurance and any chosen additions determine the actual bill. Financing may help spread the cost, but a modest vehicle should still be evaluated through total repayment. Confirm the exact Comfort configuration before comparing its instalment with a Heavy Duty advertisement.
TVS XL 100 Comfort Price in India
The manufacturer’s XL100 family page lists Comfort i-Touchstart at ₹60,480. This is the verified named configuration used as the price reference; a lower price for an unspecified Comfort should not be assumed equivalent. Heavy Duty and Win Edition are separate related offerings. The ₹72,000 assumed on-road amount below adds no invented itemised tax or insurance charge. Obtain those components from the dealer before using the model to assess an actual application. A secondary listing reverses the ₹60,180 and ₹60,480 assignments between Comfort and Win Edition. This guide retains the manufacturer’s Comfort reference; resolve that discrepancy with the dealer rather than treating either website as the invoice.
Ex-showroom is the vehicle’s advertised price before the complete ride-away bill. Obtain separate amounts for registration and road tax, insurance, and any other applicable invoiced charges. Identify optional accessories and service packages individually. Do not add tax again where it is already included in the quoted vehicle price. No exact RTO fee or insurance premium is assumed here: the finance model starts from a hypothetical complete invoice, which must be replaced with your dated quotation.
TVS XL 100 Comfort On Road Price Across Cities
For neighbourhood journeys in Gaya, Muzaffarpur or Patna, test starting and manoeuvring with the intended rider. In Agra, Varanasi and Prayagraj, consider the route and permitted load rather than assuming the Comfort can replace every scooter or motorcycle. A buyer in Faridabad or Hisar should check the registration and insurance basis for the planned use. In Indore or Bhopal, ask about local servicing and parts before accepting a distant dealer’s offer.
For wider comparison, Uttar Pradesh enquiries can cover Lucknow, Noida, Ghaziabad, Kanpur, Agra, Varanasi and Prayagraj; Haryana enquiries can cover Gurgaon/Gurugram, Faridabad, Panipat, Karnal and Hisar. Keep the registration address consistent when requesting quotes. Mumbai, Pune, Nagpur, Nashik and Thane fall within Maharashtra, but insurance and dealer packages can still differ. For Bihar, compare Patna, Gaya and Muzaffarpur; for Gujarat, Ahmedabad, Surat, Vadodara and Rajkot; for Madhya Pradesh, Bhopal, Indore, Gwalior and Jabalpur. A state name alone does not establish the final bill. A full dealer-verified city grid is not available; obtain itemised local figures rather than assigning the example invoice to every city.
For a petrol vehicle, compare the same manufacturing specification and insurance cover before judging a state-to-state price gap. A cheaper quote with fewer accessories may simply be a different package. Check each charge instead of applying an invented uniform on-road markup.
TVS XL 100 Comfort EMI: How Much Will You Pay Every Month?
All figures below are illustrative, using an assumed ₹72,000 on-road invoice and 13% nominal annual reducing-balance interest. This is not a guaranteed Drivio rate or a lender offer. Actual pricing depends on credit history, income, borrower profile, vehicle and lender eligibility. The 12–60 month choices show the mathematics; a lender may not offer every term or deposit combination, particularly for a used vehicle.
Loan amount = On-road price − Down payment. EMI = P × r × (1 + r)^N ÷ [(1 + r)^N − 1], where P is the financed principal, r is the annual rate divided by 1,200 and N is the number of monthly instalments. The calculation assumes monthly payments in arrears and no financed fees. Rupee values are rounded; the final lender schedule may adjust the last payment.
For example, a ₹72,000 purchase with ₹14,400 upfront leaves ₹57,600 to finance. At the assumed 13% for 36 months, the EMI is approximately ₹1,941. Total instalments are about ₹69,868, including ₹12,268 interest. Adding the deposit gives a purchase-and-interest outlay of roughly ₹84,268, before any fees outside the assumed invoice and ongoing ownership expenses.
TVS XL 100 Comfort Finance Options
An easy-to-use starting system can be a meaningful purchase benefit when the vehicle is used frequently for short errands. Evaluate that benefit on the cash price and full interest cost. If another family member helps pay the instalments, clarify the arrangement while remembering that the named borrower remains responsible. Keep fees visible because they can represent a material share of a small loan. Compare a shorter term if the payment remains comfortable.
Ask a bank, NBFC or dealer-arranged provider for a written personalised quotation. Typical application checks may include identity and address evidence, PAN where required, bank statements, salary evidence or business-income records, and the vehicle quotation. Requirements and minimum income vary; no universal eligibility threshold is assumed. Compare the annual percentage rate or equivalent all-in cost, processing charges, repayment schedule and total amount payable. Clarify fixed versus floating rates, late-payment charges and the prepayment terms applicable to that agreement.
A flat interest rate is not directly comparable with a reducing-balance rate carrying the same percentage. Ask for the cash flows and total repayment before choosing. If a fee is added to the principal, it also attracts interest under the agreement; if collected upfront, it raises the cash required at delivery. Either way, it should appear in the comparison.
Exploring financing through Drivio
Buyers can check the latest on-road price and explore available financing options for the TVS XL 100 Comfort through Drivio. Ask for a quote identifying the city and variant. Approval, rate, amount financed and eligibility remain subject to the lender and customer profile; no approval or lowest-rate guarantee is made here.
TVS XL 100 Comfort Down Payment
At the assumed invoice, a 10% deposit is ₹7,200 and a 40% deposit is ₹28,800. Increasing upfront cash by ₹21,600 reduces the 36-month EMI from about ₹2,183 to ₹1,456, a monthly reduction of ₹728. The 20% and 30% alternatives in the table provide intermediate choices. These percentages model the whole on-road bill; an actual lender may fund only selected invoice components, so the delivery-day cash requirement can be higher.
With 20% down, 24 months costs approximately ₹2,738 monthly and ₹8,122 total interest. Extending to 60 months reduces EMI to ₹1,311 but raises interest to ₹21,035. The longer term therefore adds about ₹12,913 interest. Choose the term using the monthly surplus left after essential spending; a lower instalment does not mean a cheaper purchase.
TVS XL 100 Comfort Running Cost
The running model assumes 600km per month at 50km/l; it is not an official mileage or payload claim. Short journeys, load and road conditions can change the result. Allow for chain maintenance, brakes and tyres, and follow the manufacturer’s operating limits. Even light usage leaves annual insurance and time-based servicing to pay. A small petrol budget should not be used to ignore these recurring obligations.
Illustrative petrol calculation: 600km ÷ 50km/l × an assumed ₹100/litre = about ₹1,200 monthly. If economy is 20% lower at 40km/l, the same travel costs ₹1,500. Petrol at ₹100 is a model input, not a verified city pump price. At the original assumption, finance plus fuel totals approximately ₹3,141 monthly. Insurance renewal, service, tyres, repairs, parking and protective equipment are additional; obtain actual quotes for those items.
Specifications and ownership implications
TVS lists a 99.7cc four-stroke engine, 3.20kW and 6.5Nm for the Comfort. It uses a centrifugal wet clutch, single-speed primary gearbox and chain final drive. This is a moped layout, not a conventional automatic scooter with the same storage arrangement.
Check the manufacturer specification for the exact year and variant: TVS XL 100 Comfort information. Untested fuel economy, battery life and service prices are not supplied as facts.
TVS XL 100 Comfort vs Other Bikes
The XL100 Heavy Duty is the nearest family comparison, but its equipment and purpose need to be checked separately. The TVS Sport and Hero HF Deluxe are functional alternatives for someone who would prefer a conventional commuter motorcycle. These are substitute transport choices, not mechanically identical rivals. Test fit, starting effort and the intended task. Compare their total purchase and ownership costs rather than assuming the lowest engine capacity gives the best result.
To translate any genuine quotation difference into finance, consider an illustrative ₹12,000 higher on-road bill. Keeping 20% down and the same 13% rate over 36 months adds ₹2,400 upfront and about ₹323 monthly. This is a comparison method, not an asserted price gap to a named competitor. Recalculate with the actual competing quotes and their own running costs.
Used TVS XL 100 Comfort Financing
For a used Comfort, establish that the starting system works reliably and examine the frame, suspension and chain. Look for signs of overloading or repairs hidden by fresh paint. Verify documents and any outstanding finance. An older low-value vehicle may not qualify for the same term or advance ratio as a new one. Keep a repair reserve and compare total outlay, because financing fees can erode the benefit of a small used purchase.
For a hypothetical used transaction, suppose the agreed price is ₹43,000, lender valuation ₹39,000, and the advance 75% of that valuation. Finance would be ₹29,250, leaving ₹13,750 cash before transfer costs and fees. At an illustrative 14% over 24 months, EMI is ₹1,404. These are invented transaction inputs for calculation, not observed resale prices or an available offer. Confirm outstanding hypothecation and the applicable ownership-transfer process before payment.
Who Should Consider the TVS XL 100 Comfort?
The Comfort can suit local utility travel when its layout and permitted capabilities match the rider’s needs. It should be chosen after a practical test rather than from a low-EMI card. Someone requiring scooter storage or regular longer journeys should examine alternatives. Keep the transaction simple: the exact vehicle, itemised on-road price, affordable deposit and clear repayment schedule matter more than an oversized list of optional extras.
Is Financing the TVS XL 100 Comfort a Good Option?
Use your own transport allowance rather than a universal salary rule. For illustration, an allowance of ₹5,000 minus the modelled ₹1,941 EMI and ₹1,200 petrol leaves about ₹1,859 monthly for insurance reserves, service, tyres, parking and contingencies. This is a budgeting example, not an income eligibility threshold. If your actual bills exceed the remainder, adjust the deposit, variant, term or purchase timing. Existing debt and essential household spending come first in that calculation.
The XL100 Comfort i-Touchstart has a manufacturer price reference of ₹60,480; local on-road charges remain additional. On an assumed ₹72,000 bill, 20% down payment gives approximately ₹1,941 EMI at 13% for 36 months. Assess starting convenience, permitted use and maintenance before financing. Small-loan fees can influence value materially, so compare total repayment. Check the exact model’s current quotation and explore finance through Drivio, subject to lender eligibility and the borrower’s final approved terms.